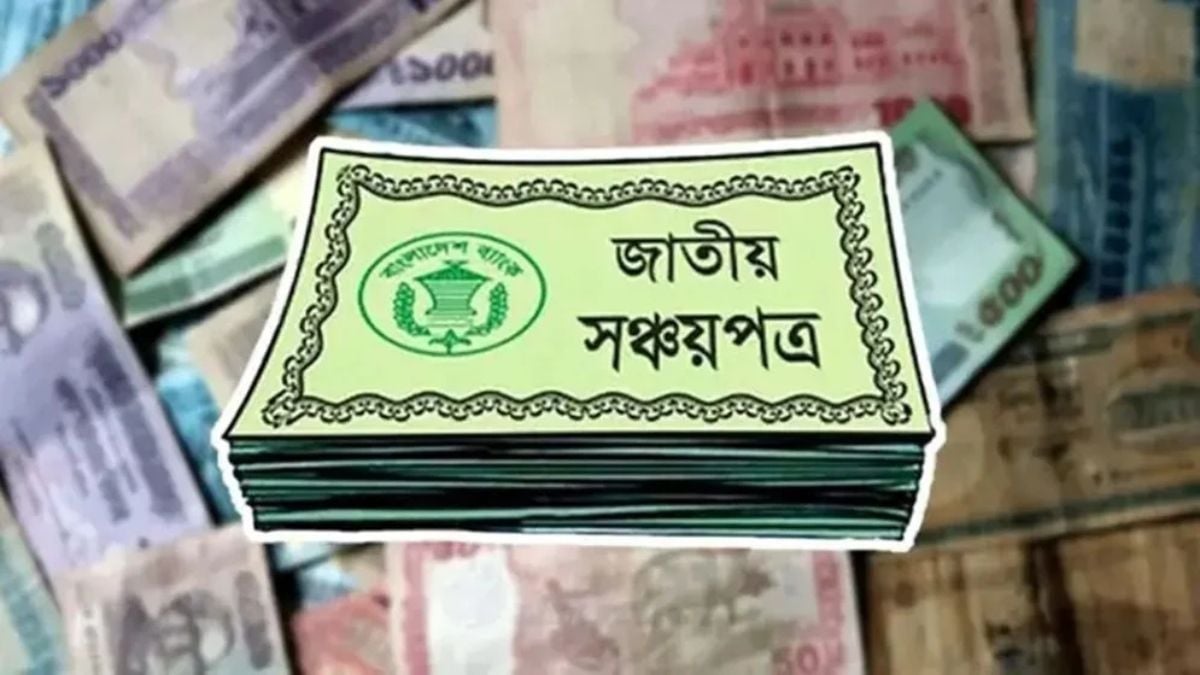
Under the new rules, those whose actual tax rate is less than 10 percent may benefit; those whose tax rate is more than 10 percent may have to pay additional tax. For example, if an individual receives one lakh taka in profit from a savings certificate in a year, 10,000 taka is deducted at source at the rate of 10 percent. If his total income, including three and a half lakh taka from other sources, is four and a half lakh taka, the applicable tax stands at five thousand taka — in that case, he will have the opportunity to get back five thousand taka of the amount deducted at source. On the other hand, if the profit is five lakh taka and income from other sources is four lakh taka, making total income nine lakh taka, the applicable tax will be 60,000 taka; after adjusting the 50,000 taka deducted at source, another 10,000 taka will have to be paid.
To get a refund of excess tax, filing an income tax return is mandatory. The refund must be applied for by providing bank account information in the return, and proof of tax deducted at source must be submitted. Those whose income is within the tax-free limit but from whose profits tax is being deducted at source must also obtain a TIN and file a return. After verification and scrutiny by the tax department, there is a provision to refund the due amount to the bank account within 120 days. As a result, low-income savers will benefit, but for persons with higher income and higher tax rates, the amount of tax may increase.